•  

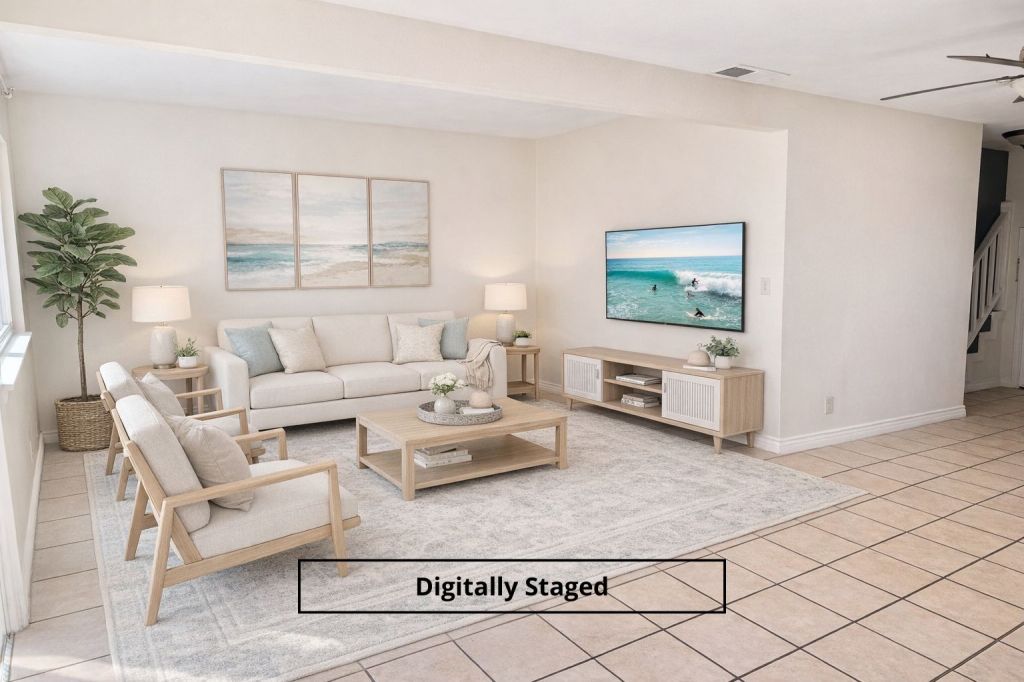
    Mission Viejo property with investment potential
    Active Mission Viejo potential investment property listed at 399K

    Hi everyone!

    Had a great meeting last week with a young investor – he’s decided its time to buy his first investment property!  Investing in real estate doesn’t have to be difficult and complicated, especially in this market.  This 30-something noticed that he could get a home cheaper now than when he bought his first home 6 years ago, and he also noticed that he may be able to break even on it!  Hmmm…that got him thinking about investing in real estate…something his father was always talking about.

    To confirm his suspicions, he had me pull the rental rates in Mission Viejo, San Clemente, Aliso Viejo, Lake Forest, and Laguna Niguel.  All cities averaged in the $2400-2800/mo range for 3 bed properties 1500-2000 square feet.   (Attention renters, that means you can BUY cheaper than leasing right now)

    After that, we went back to his lender and confirmed that if he put down 3% on a Fannie Mae loan, his payment for a property around 400K would be approximately $2000-2200/mo.  Interest rates are THAT good right now 🙂  Exciting news – he can IMMEDIATELY cover the spread with a tenant, even with a gardener or a small HOA!

    To put the plan in action, this week we’ll go looking at detached properties in the above cities under 400K.  There are actually a lot of properties for him to choose from right now, believe it or not.  54 if you’d like the exact number.  We’re really excited to get such a young investor going in such a sweet market.  I asked him if he’s read “The Automatic Millionaire Homeowner” by David Bach, but he hasn’t yet.  I let him know he’s already implementing the concepts within the book – what a smart cookie 🙂

    Real Estate Investing Can be Easy

    Investing doesn’t have to be really complicated or difficult – it just needs to be done with a long term plan and strategy.  This investor’s long term plan is to have someone ELSE pay off his 2nd property, and then when he and his fiancee decide to settle down and have children, use some of the ‘extra’ he is making to enjoy an upgrade of his own.

    If you have any questions about Orange County real estate investing, don’t hesitate to contact us.  Of course, we have the spreadsheets that will do the complicated numbers and math if you want them.  But sometimes, its just logical and easy.  How do you like to invest?  What formulas do you use?  Comment below or tweet @weeksteam or @angieweeks and share  your strategies!!

  • Mission Viejo lake from the MissionViejo.org blog
    Mission Viejo lake from the MissionViejo.org official city blog

    Mission Viejo Real Estate is aplenty right now 🙂  How many homes do you think are on the market and available?  Here’s the stats!!

    Active: 262
    Attached: 89
    Detached: 171

    Backup: 168
    Pending: 66
    Closed: 86 (in the past 30 days)

    Lots of moving going on!  We compared this to the same timeframe one year ago, and there were 80 closed sales…meaning the market in Mission Viejo is steady if not a little up.

    Since we’ll be doing a more reporting on Mission Viejo Real Estate this year, now is a great time to explain what these ‘status’ labels actually mean.

    • Active – indicates the property is on the market and accepting buyer offers.
    • Backup – means the home has technically accepted a buyer offer and is sold, but the buyer is still in his/her contingency period of due diligence investigations and full loan approval.  California buyers get 17 days after offer acceptance to complete all contingencies and inspections.
    • Pending – implies all contingencies have been removed on this listing and its only a matter of time until close.
    • Closed – entails the buyer’s loan has funded, and title has officially recorded in the new owner’s name.

    There are a few other status’ you may see:

    • Hold – property is on hold and not being shown to new buyers for various reasons. (there are 36 of those right now)
    • Cancelled – means the property listing was cancelled by the owner before a sale took place.
    • Expired – indicates the listing agreement on the home for sale expired before a sale occured.
    • Withdrawn – similiar to cancelled status, this property has been withdrawn from the market.

    Its interesting to note that comparing the last 30 days to the same period one year ago, the price per square foot has gone DOWN, but the average sales price and days on the market has gone UP:

    Average sale price in Mission Viejo 1 year ago:  $435,042
    Average sale price in MV over the last 30 days:  $467,640

    Average price per square foot 1 year ago:  $262.50
    Average price per square foot today:  $240.84

    Average days on market 1 year ago:  93
    Average days on market now:  108

    According to the stats, it sounds like buyers are still getting more square feet for their money 🙂  That combined with super low interest rates makes buying a home in Mission Viejo or relocating anywhere in Orange County ideal!

    For some additional perspectives on business, commerce, and fun in Mission Viejo here is the current State of the City:

    Contact The Weeks Team today at 877-230-3211 for more information, or click to start searching right now for your new home in Mission Viejo!

  • First time buyer Orange CountyAs first time buyer specialists, we’re constantly helping buyers address their fears about purchasing real estate. Some are very valid, while others are simply fear of the unknown. If you know someone going through pre-homebuying drama , please share this post with them, so they know they’re not alone, and understand how to overcome! 🙂

    1. Fear of getting rejected.

    There are WAY too many renters missing out on today’s buyer’s market simply because they are afraid to get qualified. They’re afraid that one bill they forgot to pay 5 years ago or those charged off accounts from college will keep them from buying a home forever. This is NOT true!! Everyone has dings on their credit, it does not mean you’ll be excluded from buying a home.  At least talk to a lender and see what steps you need to take next to get qualified.  Interest rates are ROCK BOTTOM right now, you owe it to yourself to try 🙂

    2. Fear of losing good faith deposit.

    A typical California ‘Good faith’ deposit (GFD) is 3% of the purchase price. Buyers write a ‘Good faith’ check and submit it with their offer, and if their offer is selected, the check is cashed and the escrow process begins. We’ve seen lots of buyers hesitate to write this check because they believe once the check clears, they MUST buy that property. In California, this is FAR from the truth. Your GFD is simply funds you as the buyer put forward to show your commitment to the property as you do your due diligence. During this due diligence contingency period, you can decide against the property and have your deposit returned for any reason, so don’t lose a great property because you are in fear of making a deposit!

    3. Fear of overpaying.

    Even though today’s buyers know the market better than ever with access to the MLS via internet and home value apps everywhere, buyers are still afraid to make a move in fear they will have ‘overpaid’ for a property they fell in love with, and be stuck underwater for years and years. (Sound like any renters you know??) Nothing could be further from the truth. Unless you are paying CASH for a property, it’s impossible for you to overpay, because there are systems of checks and balances in place to ensure this does not happen. During your ‘due diligence’ period, your lender is also doing their due diligence to make sure this is a solid property to loan you money on. The lender will send out an appraiser, and the appraiser’s sole job is to confirm the property is worth the price you offered on it. So rest easy knowing the bank will never loan you more money than the property is worth, even if you wanted to overpay. Plus, having an experienced buyers agent as your Realtor will also help you avoid overpaying, so you’re double covered 🙂

    4. Fear of choosing a lemon.

    We’ve all seen “The Money Pit” with Tom Hanks….YIKES! There are a lot of people out there who believe sellers will lie, cheat and steal to get their property sold. (and sometimes they may try to!) Fortunately for today’s homebuyers, a property inspection is conducted to ensure the home you love is not a lemon. There are quality home inspectors all over Orange County and they will inspect your property while its in escrow to make sure all the electrical, plumbing, appliances and structure is in working order. After a buyer’s inspection is complete, it is also typical to submit a ‘request for repairs’ to the seller with a list of items you would like addressed before moving into the property. Every property will have its problems, but buyers will always go into the situation with eyes wide open as long as they get a a property inspection with a quality inspector.

    5. Fear of overextending.

    Another completely valid buyer fear is over extension. “What if I bite off more than I can chew”? “What if I get laid off”? “What if I need to move”? These are all GOOD things to consider, but, they are not reasons why you should rent in fear the rest of your life. Actually, if you rent until you retire, you’re going to have a lot of reasons to worry how you’ll keep the roof over your head. Ideally, you’ll purchase a property, pay down the mortgage, and live in your paid off property after retirement 😉 In order to safeguard your investment, its a really good idea to have 3-6 months worth of reserves in the bank in case you do lose your job or need to move and find a renter for your property.  Talk to your financial advisor about how much you should have in reserves so you don’t overextend and have to eat ramen noodles for the rest of your life.  Its bad for your health.

    What makes you hesitate to buy a home? If you’ve already bought your first property, do you remember your biggest fear when you took the plunge the first time? Please share by commenting below or tweeting @weeksteam or @angieweeks – we’d love to hear your story!!

  • EZ Choice Financial Corp *****ATTENTION REALTORS AND LENDERS*****Let us show you how we can help you build a great pipeline.  Many of the families that are interested in purchasing homes these days have credit issues of some sort.  We can help you cultivate them.  We are experts in building relationships with your clients and keeping them excited while we will help them fix their credit so that they will return to you ready to qualify.  DO NOT TURN THEM AWAY!! We can provide an on site presentation to show your realtor’s, in house lender’s and broker’s what set’s us apart from other credit repair companies.  Call now for more details 888-349-6690

  • With so many foreclosures and short sales happening now, we can help!  Give our Office a call now for a FREE CREDIT EVALUATION.  (888) 349-6690 http://www.ezchoicefinancial.com

  • Hello Everyone,

    My name is Manny Moumdjian, the founder of EZ Choice Financial Corp. There are still Ethical and Integral Credit Repair Companies out there that can help you with your credit worthiness. Having over 15 Years of experience in Credit Repair and Rebuilding Credit. Our Credit Repair Service Guarantees improvement within a 6 month period or a 100% Refund with No questions asked! We are Experts in finding multiple errors on credit reports and getting them corrected, updated or deleted from the 3 Major Credit Bureaus permanently! We give consumers Hope on getting their credit back on track to qualify in the very near future for a home or vehicle and even certain credit cards and just having a stress free quality of life! W are Fully Bonded in the State of California and Registered with The Secretary Of State and Department Of Justice. Everyone receives a free consultation! All pricing is calculated by what is on the credit reports and we offer everyone an affordable payment plan. Call us for a Free Credit Evaluation today (888) 349-6690

  • I’m astounded at how many Orange County homeowners qualify for a loan modification. And I’m even more astounded that they never seize the opportunity, generally because there’s so much misinformation floating around. As a result, hundreds of distressed homeowners never get the help they need. Mike Hatcher, seasoned modification advisor with the Ascent Network, is here again to offer a wealth of valuable insights —

    The best thing I can do is clear away all the debris of misinformation.  So, in no particular order, here’s a list of GREAT loan modification candidates:

    • Those yearning to save an average of $1,000 a month — our average improvement.
    • Those with W2 income between $40k-$130k. Or the self employed, who usually don’t qualify for a refinance. We are 99% successful securing modifications for this group.
    • Those who never “rob Peter to pay Paul” in order to cover the bills.
    • Those who have perfect payment records but wonder how long they can afford to make their payments.
    • Those in default and are 14 days from a foreclosure sale on their property.
    • People worried sleepless because they fear losing their home and fear seeking help. This reluctance typically is the result of mass misinformation.
    • Those who want to shoot their spouse (or realtor) for deciding to purchase the house back in the mid-2000s.
    • Individuals seeking a long-term mortgage solution with a fixed rate.
    • Those who realize that renting ultimately costs more, don’t want to pay for or expend the energy for a move, and don’t want to live in someone else’s rental property.
    • Those who fail to qualify with their lender, or are given a token $30-$100 monthly savings modification as a consolation prize.

    Quite a list, with more than a few surprises, eh? So, are you ready to learn how a loan  modification can put $1,000 extra in your pocket every month? Just call Mike at 877.871.2400  x15.  You’ll be amazed at how simple it is to cast your financial worries to the wind.

    And, of course, if you’d like to learn more about the variety of opportunities the Orange County real estate market offers, I’ll be delighted to help. Just call, tweet, or email me at 949.338.7408,   @AngieWeeks, @WeeksTeam, or  angie@askangie.com.  I’m ready to assist you in any way I can.

  • You all know that Orange County homeowners can reap substantial rewards from loan modifications.  But were you aware that loan mods are a great avenue for investors as well? Believe it or not, most investors can qualify for this excellent financial option. Here’s a quick overview by Mike Hatcher, seasoned modification advisor with the Ascent Network —

    Here at the Ascent Network, a faith-based, non-profit organization, we offer a number of outstanding options for investors. Thanks to our experienced and knowledgeable team, we’ve helped thousands of clients since 2007.  And one of the major ways is by securing loan modifications for investors. Why should you pursue a loan mod if you’re an investor? Here are the five top reasons:

    1.   Income qualification is based on Profit and Loss (P&L), which we help put together for you, not your tax return. A P&L is a great asset. That’s because, depending on your debt to income thresholds, deductions may or may not be applied to ensure the best fit for a client.

    2.   Our average, the investor modification rate is 4.25-4.5%

    3.   This is a fixed rate.

    4.   The term typically is 30 years, with some going as long as 40 years. For the record, 30% of lenders consider a 40-year term.

    5.   We negotiate successful outcomes with 80% of our clients.

    Would you like to learn how modification can help you leverage the value of your investment property to put more cash in your pocket on a monthly basis? Call Mike at 877.871.2400 x15, and boost the cash flow from your investment property.

    And, of course, if you’d like to learn more about the variety of opportunities the Orange County real estate market offers, I’ll be delighted to help. Just call, tweet, or email me at 949.338.7408,   @AngieWeeks, @WeeksTeam, or  angie@askangie.com.  I’m ready to assist you in any way I can.

  • VA LoansHey Orange County Veterans!  Here’s a great article about VA loans from OCAR mag, reprinted with permission here on our blog.  If you’re interested in a VA loan or getting a home with your veteran benefits please contact the AskAngie team at 877-230-3211!

    VA Loans on the Rise

    With deployment looming and more veterans entering the workforce soon, Realtors might want to brush up on the basics of VA financing.  A VA (Veterans Administration) guaranteed home loan is the preferred loan program for Active (and non-active), Reserve, National Guard, and retired military of the armed forces because there is no down payment needed, the interest rates are low, and no private monthly mortgage insurance is required.

    An interesting fact — more than 27 million veterans and service personnel are eligible for VA financing.  This is a growing buyer segment for the real estate community.

    Veteran Loans – Do I Qualify?

    To be eligible for a VA loan, Wartime/Conflict Veterans must serve for at least 90 days and must receive an honorable discharge.  Here are the dates of active duty:

    • World War II – September 16, 1940 to July 25, 1947
    • Korean Conflict – June 27, 1950 to January 31, 1955
    • Vietnam Era – August 5, 1964 to May 7, 1975
    • Persian Gulf War – Check with VA regional office for specific eligibility.
    • Afghanistan and Iraq – Check the VA’s Web site for eligibility guidelines for current service in Afghanistan and Iraq.

    Reserves and National Guard – Members who have completed six years of service and have been honorably discharged (or are still serving) may be eligible for a VA loan.

    For peacetime service, an applicant must have at least 181 days of continuous active duty with no dishonorable discharge. If discharged earlier due to a service-connected disability, the applicant must contact the regional VA office to verify eligibility.

    8 Things Realtor’s & Vets Should Know about VA Loans:

    1. 100% financing – No down, Zero Down.   Unlike an FHA loan (3.5% down) or a conventional loan (3-5% down), a VA loan requires no down payment.
    2. No monthly private mortgage insurance is required.  Unlike a low down FHA or a no down Conventional loan (which require PMI), a VA loan has no PMI.
    3. 4% seller credit is okay — There is a limitation on buyers closing costs.  FHA and Conventional loans allow for a 6% seller credit, but VA loans cap this credit at 4%.
    4. VA is not a lender — VA does not actually lend the money to you directly. Instead, the VA offers a guaranty to lenders, like me, that if the loan goes into default, they will pay the lender a percentage of the loan balance. The word GUARANTY does not actually guaranty the veteran will qualify for a VA home loan.  Instead, it’s a “guaranty” that the lender will not incur losses in case the VA borrower hits hard times and a foreclosure ever develops.
    5. Interest rates are low – The interest rates are similar to FHA rates.
    6. You don’t need perfect credit – Most lenders require at least a 620 FICO score, but some lenders will go as low as 580, if certain conditions are met.
    7. The VA defines allowable fees and charges that the veteran borrower can pay or closing costs that may be charged to the borrower. These costs are determined as reasonable and customary by each local VA office. All other costs in the transaction are considered non-allowable and generally paid by the seller when purchasing a new home or by the lender when refinancing your current VA mortgage. Allowable fees are appraisal, inspections, recording fees, credit report, prepaid items, hazard insurance, flood check, survey, title insurance, and VA funding fee.
    8. The VA also specifies what is NOT allowable.  Additional fees may be charged to the veteran only if specifically authorized by VA. The lender may request VA to approve such a fee if it is, (a) normally paid by the borrower in a particular jurisdiction, and, (b) considered reasonable and customary in the jurisdiction.  The following list provides examples of items that CANNOT be charged to the veteran as “itemized fees and charges.” Instead, the lender must cover any cost of these items out of its flat 1% fee.   Non-allowable fees include:  Loan closing or settlement fees, underwriting, processing, escrow fees, notary, document preparation fees, preparing loan papers or conveyance fees, attorneys services other than for title work, photographs, interest rate lock-in fees,  escrow fees, broker fees by third party mortgage brokers and tax service fees.

    PAUL E. SCHEPER, MBA, CSA, SRES is a devoted member of OCAR.  He is a graduate from Harvard University and USC.  He is a licensed mortgage banker and OC VA loan specialist since 1984.

  • 796 W Lambnert # 157, La Habra, Ca
    Condo  (not listed)

    1 bed/ 1 bath
    700 sq feet
    approx list price to be 125K

    6029 Moraga, Riverside, Ca

    SFR
    3 bed/2 bath
    2500 sq ft
    single story
    no HOA
    coming to market soon, no price yet
    estimated price to be 200-230K

    30542 Paradise Palm, Homeland, Ca 92548
     

    Senior living mobile home with golf course
    2 bed 2 bath
    2040 sq ft
    Listing Price: $65,000

    7223 Comstock #C, Whittier, Ca
    Condo

    2 bed/2 bath
    1291 sq ft
    assoc pool/spa
    HOA $225
    good condition
    model match in escrow for $225K
    List price is $213,000
    7722 Friends Ave, Whittier, Ca
    SFR needing a lot of work

    1234 Sq Ft
    3 bed/ 1 bath
    NO HOA
    detached garage
    28549 Cilla Ct, Romoland, Ca

    Coming to market

    SFR
    4 bed/2 bath
    1460 sq ft
    tenant occupied
    No pictures
    Call Angie Weeks (949.338.7408) directly if you’re interested in any of these properties 🙂
  • If you’re in the market for a new home, but don’t have enough money?  Now your problems are solved!  Kara Collacott, of Essex Mortgage, just told us about a new down payment assistance program for ANYONE, not just first time buyers!  This program will give you 3% down for an FHA loan.  The qualifications are:

    *ratios 39.9/49.9

    *1 month cash reserves after closing

    *AUS accept only

    *Single Family Residence or approved Condos/PUD NO UNITS

    *Purchase Only

    *Borrowers must complete 8 hour home education program

    *Must have 90 day income and expense analysis with no payment shock

    *Buyer is allowed to move without needing to refi or sell the property

    Seems easy enough with a promise of living in the house of your dreams!  Contact Kara at (714) 935-2581 ext. 294, or on her cell:  (714) 469-2629, or e-mail her directly at kcollacott@essexmortgage.com if you have any questions or want more information!

  • As if there weren’t a bonanza of incentives already available to first time homebuyers, newbies have yet another excellent reason to purchase a house. Called Homepath, this very generous program currently enables Fannie Mae to offer buyers up to 3.5% in closing cost assistance through October 31, 2011.  In addition, a $1,200 selling agent bonus is available to agents who close on an owner occupant property and meet all eligibility requirements and terms and conditions. 

    Remember, Homepath is available only for Fannie Mae properties and to first time buyers. If you and your chosen property qualify, the program offers you a fantastic way to get some amazing benefits. Possibilities include getting your closing costs paid or changing a prohibitively costly condo into an affordable dream home.

    If you’re interested in Homepath, here are some of the conditions you should be aware of.

    • Buyers and/or selling agents (the agent representing the buyer) must request the incentive upon submission of initial offer.
    • Initial offer must be submitted on or after June 14, 2011 and close by October 31, 2011. Initial offers made prior to June 14 are not eligible for the June 14 – October 31 incentive.
    • Sale must close on or before October 31, 2011. No exceptions will be made to this deadline. (Note: Initial offers submitted after September 15, 2011 may not close by the incentive deadline of October 31, 2011.)

    If you’d like to learn more about Homepath, I’ll be delighted to help. Just call, tweet, or email me at 949.338.7408,   @AngieWeeks, @WeeksTeam, or  angie@askangie.com.  I’m ready to assist you in any way I can.

  • Like any investors, those delving into Orange County real estate want the best possible deal. Great. But investors also need to temper their profit quest with a sound strategy and realistic expectations. Getting a good deal boils down to four essentials:

    1. Decide how much you want to spend.
    2. Determine your intention. Do you want a portfolio piece or a buy & flip?
    3. Know how to recognize a good deal.  After determining market value and identifying the desired neighborhood, an investor who gets a property at 10 percent below market value definitely is getting a  DEAL.
    4. Factor in the REAL numbers. How much are expenses, upgrades, commissions, rents, etc.?

    I gained a few additional insights from John, a full time courthouse steps investor. According to him, if you make 10-15% on a foreclosure, you’ve done mighty good for yourself. Remember, the key to making a profit is how fast you can move the property or turn your money.  

    John added that many investors seek unfinancable condos. That’s because the more difficult it is to buy a home, the more its value drops. Many investors buy condos to hold for 5-10 yrs, hoping the hoa recovers and the property significantly appreciates. He pointed out that condos in college towns are in fairly high demand because of their proximity to the local campus.

    If you’re scouring the marketplace for investment possibilities and want to do some number crunching, I can provide you with a very useful spreadsheet. Just call, tweet, or email me at 949.338.7408,   @AngieWeeks, @WeeksTeam, or  angie@askangie.com.  I’m ready to assist you in any way I can.

  • This post is for any of the OCYPN members who didn’t make our Lunch & Learn today – the info is too good not to share!  Ryan Spitalnick, Prominent Escrow’s in house attorney, shared his strategies for getting HOA liens reduced so our OC short sale deals can get closed!  

    Spitalnick stated any reasonable HOA already knows they are in a 2nd or 3rd lienholder position, and they already know its very likely they  get absolutely nothing if the short sale goes into foreclosure 😦

    …but…sometimes Homeowner’s Associations are still stubborn about back dues owed.  This can cause good escrows to fall apart, and properties to go into foreclosure 😦  Ryan gave YPN 5 negotiation tips that he uses to get discounts on HOA demands.

    What to say to the HOA??

    Tip 1:  “The law is not in your favor” 

    Some HOA’s forget there is a pecking order in which property liens are paid.  The main mortgage always gets paid first, and then a 2nd mortgage and taxes, then HELOC’s, HOA’s, and other liens. 

    Tip 2:  “The short sale lender is offering money now that will not be there if the property goes into foreclosure”

    If a foreclosure occurs, all secondary liens mentioned above are NOT the responsibility of the new homeowner (bank or investor) to absorb.  The secondary liens are then forced to go after the foreclosed homeowner personally if they want to recoup the unpaid debt.  Now is a window of opportunity for the HOA to get something instead of possibly nothing at all.

    Tip 3:  “The HOA will end up spending good money chasing bad”

    Even though HOA’s have the right to go after the foreclosed homeowner for back dues, what is the likeliness that person has the ability to pay?  In addition to attorney fees, collection costs, and time spent, the HOA faces never getting their money after spending plenty of funds trying.

    Tip 4:  “Remember the bank or an REO sale is not responsible for paying back dues”

    Many HOA’s will say “I’m entitled” to the full amount.l  Technically, they are.  But in a short sale everyone involved is losing money, and the HOA should not expect to be any different.  Many times the HOA’s own CC&R’s state reminders they are not the primary lienholder in multiple places, so make sure you have a copy handy to point it out!  Short sales are designed for debtors to recoup as many costs as possible and cut losses.  Junior lienholders always get hit the worst 😦  Discuss this with your HOA contact and request a revised and discounted demand.

    Tip 5:  “Do you really want to force a vacancy for minimum 6-12 months on the slim chance you will get a payment?”

    If the HOA does not revise their demand and the property is foreclosed, it will be vacant and there will be nobody paying monthly dues for the unit.  On the other hand, if they accept less on the current amount owed, they will have a new homeowner within 60 days paying dues on the unit again.  Knowing there is a slim chance the old owner will pay anyway, why not cut losses now and save vacancy and possible vandalism fees?

    If you’re still having trouble, keep in mind that HOA’s typically have an attorney advising their board or property management company.   The person you are talking to on the phone is probably NOT the decision maker.  If you have to, work your way to the attorney or decision maker directly so you can be most effective in negotiations. 

    If you’d like more info on CA condo law, download the free Davis Stirling app or consult with a Real Estate Attorney like Ryan 🙂 

    Also, if you’re an Orange County Realtor interested in joining YPN, membership is FREE and you’ll get tons of valuable real estate tips just like this to help you close more deals and better serve your clients.  Like us on Facebook and check the group out!

  • Alright, you’re thinking about upgrading your home. But along with those new faucets, fresh paint, and vinyl tiles, did you ever consider all the eco-friendly improvements that will add pizzazz to your property and boost the health and well being of our planet? These days, the possibilities for GREENgrading your home are virtually limitless. The choices fall into three budget categories.  Here are a few suggestions from each category –

    LOW COST

    • Use CFC or LED light bulbs – Far more energy efficient than conventional bulbs
    • Insulate hot water heater – Can reduce standby heat losses by 25%–45%
    • Install motion sensors in offices and other common use area conference rooms to turn off lights when not in use
    • Install water efficient restroom fixtures – Reduces water use and saves you big bucks
    • Provide recycle bins

    MEDIUM COST

    • Tune up HVAC – Improves both efficiency and comfort
    • Replace hardwood flooring with bamboo or cork floors – Will keep your home warmer in the winter and cooler in the summer.
    • Insulate attic and other areas
    • Buy recycled office products and equipment
    • Provide on-site bike room to encourage environmentally friendly commuting

    HIGH COST

    • Buy ENERGY STAR appliances – Lower utility bills, better performance, and greater durability.
    • Replace roof with reusable/recyclable materials
    • Replace cabinets with sustainably harvested wood and low-VOC finishes – This type of wood comes from a certified wood harvesting site, not an unsustainably logged region, which can have a negative impact on the environment. Low VOC substances have less odor and impact on air quality.
    • Implement super energy efficient transformers – Reduces energy use and CO2 emissions.
    • Implement on-site water reclamation system – Save water and money on water bills.

    Those are just a few of the GREENgrading options you can take advantage of. Hopefully you have some of your own eco-friendly tips. We’d love to hear about them. Just fire off your ideas below. Or tweet @weeksteam with #green.

    And be sure to reach out to us if you have any questions. You can connect with our green team at 949.338.7408 or  angie@askangie.com,  @AngieWeeks or @WeeksTeam.

  • We asked one of our friends in lending to give us the sizzling summer deals.  Here’s an option for option for safely getting more home for less from Barry Zanck.  “I give away money” is my common reply when queried about my profession. Well, there is of course a hitch being that we take your house as collateral and, if you don’t pay us back..… Okay, my favorite loan program is a 10/1 adjustable rate mortgage that has a fixed rate for the first ten years. The advantage? Almost 1.5% below the 30 year fixed rate and still a Fannie/Freddie loan with no prepayment penalty. Since the average loan is kept only 4.3 years and you are allowed to prepay all the principle you want, this loan can offer some real interest rate savings. For example at $400,000 30 year fixed at 4.5 % (4.622%APR) has a 30 year payment of $2026.74. A 10/1ARM has a 10 year set payment of $1740.83 3.25% (3.421%APR) for a savings of $285.91 monthly! Now, throw just a little more than half that savings into principle reduction and you 10 year loan can be a 15 year fully paid off loan!
    Call me, I have other ideas that work just as well.

    Barry E. Zanck
    Americap Direct Funding
    DRE Brk #01082108  NMLS #243592
    (949)910-4445

  • “As Orange County realtors with specialization in Laguna properties, the Weeks team has been successful at helping folks just like yourself actualize your dreams and own a piece of Laguna Hills real estate.   It is always recommended that you consult a financial advisor when it comes to a large purchase, but don’t be surprised if you find out that you may qualify as a candidate to own Laguna Hills real estate!”  –  “Laguna Hills Real Estate –  Creative and Savvy Ways to Own”, OC METRO.

    Though many people don’t see themselves as potential homeowners, most people with somewhat decent credit just need to think outside the box a little to get into a home. Whether its sharing payments with roommates, using another property as leverge, or having a family member co-sign, it may take creativity to get that Laguna Hills real estate you’ve always wanted.  Find out what some creaive homeowners did to afford their Laguna Hills real estate!

    Click here to read the full article, entitled, “Laguna Hills Real Estate –  Creative and Savvy Ways to Own”.

  • Loan Modification You Can Trust
    I say that you can trust because of the following four reasons.
     
    … Our Results
    80% Success with all clients.
    9 out of 10 of these — we negotiated a 2% rate.
    99% success rate for the self employed.
    The 20% we are unsuccessful are due to income loss/changes for W2 applicants.
     
    … Our Non-profit Status
    Law changes now require all Modification Entities to be a Non-profit.
    We started the process to change to a Non-profit two years ago.
    Now, the people of the state of California officially own the company.
     
    … Our Experience
    We have modification experience with all the major lenders since 2007.
    We know the modification guidelines require for success.
    Our process will stop the foreclosure sale of the property.
     
    …Our References
    Hearing from a past client is one of the best methods of building comfort to trust a company.
    We hope you take time to look at our website at www.theascentnetwork.org.
    There at the website you can read many statements sent to us by past clients.
     
     
    Here’s The Problem Many Homeowners Face
    ·         1 out of 3 homeowners are in trouble making their mortgage payments.
    ·         99% of homeowners are unsuccessful to negotiate a modification directly with their lender.
    ·         Many have sleepless nights worrying about whether they will lose their home.
    ·         Being self-employed, the tax return income is not enough to qualify for a refinance.
     
     
    And, The Solution We Offer
    ·         90% of our successful cases start with a 2% rate over 40 years.
    ·         Security to keep your home while we work on your modification.
    ·         We negotiate deferment of outstanding payments due on the loan.
    ·         During your modification process financial breathing room is created.
    ·         Our fee is only $1595 of which $100 is not due until we are successful.
     
     
    Most of our clients see in a new payment structure.
     
    Loan Amount                                 Payment
    $300,000                                            $600
    $400,000                                            $900
    $500,000                                            $1200
    $600,000                                            $1500
     
     
    These payments are usually half of what are currently being paid by most. There has never been a loan available that is this good for the very best of qualifying people.

  • Alright, you’ve decided to enhance the value and the beauty of your Orange County home with some first-rate landscaping. In preparation, you’ve no doubt pondered issues like space, style, and plant choice until your head hurts. But have you stopped to consider the environmental impact of your home improvement  project? The good news is that you can boost the beauty of your home and help keep our planet green simply by considering factors like water use, runoff, and sustainability in your landscaping strategy.

    How Green is Your Roof?

    One good way to score high points in these areas is by growing native fruits and veggies on your property. Indigenous plants already fit perfectly into the ecosystem. Since this type of foliage naturally belongs in the region, it requires less irrigation and less pest control than your average outsider. To save even more precious H2O, group together all plants with similar irrigation needs.  Plants that drink together, save water together.

    You’ll also want to retain the maximum amount of natural landscaping. Keeping an abundance of native plant life in place does wonders to minimize runoff.

    On the fertilizing front, composting is an effective, eco-friendly way to liven up your soil.  Check out Home Depot. They offer an excellent selection of easy composting solutions that will jump start your future of fertilizing.

    OK. That’s it from this end of the planet. Does anyone else out there have some eco-friendly landscaping suggestions? We’d love to hear about them. Just fire off your ideas below. Or tweet @weeksteam with #green.

    And be sure to reach out to us if you have any questions. You can connect with our green team at 949.338.7408 or  angie@askangie.com,  @AngieWeeks or @WeeksTeam.

  • Whether you’re moving into or out of an Orange County home, you probably have a ton of stuff to lug along on your journey. And that, of course, means you’ll be needing an assortment of boxes and other packing materials for the thousand and one household belongings you’ve accumulated over the years. Now what if you could get your hands on the required packing materials and be a friend to the environment all at the same time?  You can with Green Packaging. This outstanding service will provide you with everything from boxes made of recycled materials to biodegradable poly bags. Once you have the needed boxes, make sure you reuse the heck out of them. And when the hard-working boxes have served their purpose, give them to somebody else to use over and over and over again. Both the recipients and our planet will appreciate the gesture.

    But packing is just a starting point. Here are a few other eco-friendly solutions for folks on the move —

    • Don’t trash unwanted items. De-clutter by connecting with CraigsList or freecycle.com. And be aware that the Habitat for Humanity Restore will gladly accept virtually any of your donated belongings. After all, one person’s trash is another man’s treasure.
    • Request a green termite clearance.
    • If re-doing landscaping, consider using native plants to reduce water use and runoff.

    Does anyone else have some eco-friendly suggestions for people on the move? We’d love to hear about them. Just fire off your ideas below. Or tweet @weeksteam with #green.

    And be sure to reach out to us if you have any questions. You can connect with our green team at 949.338.7408 or  angie@askangie.com,  @AngieWeeks or @WeeksTeam.